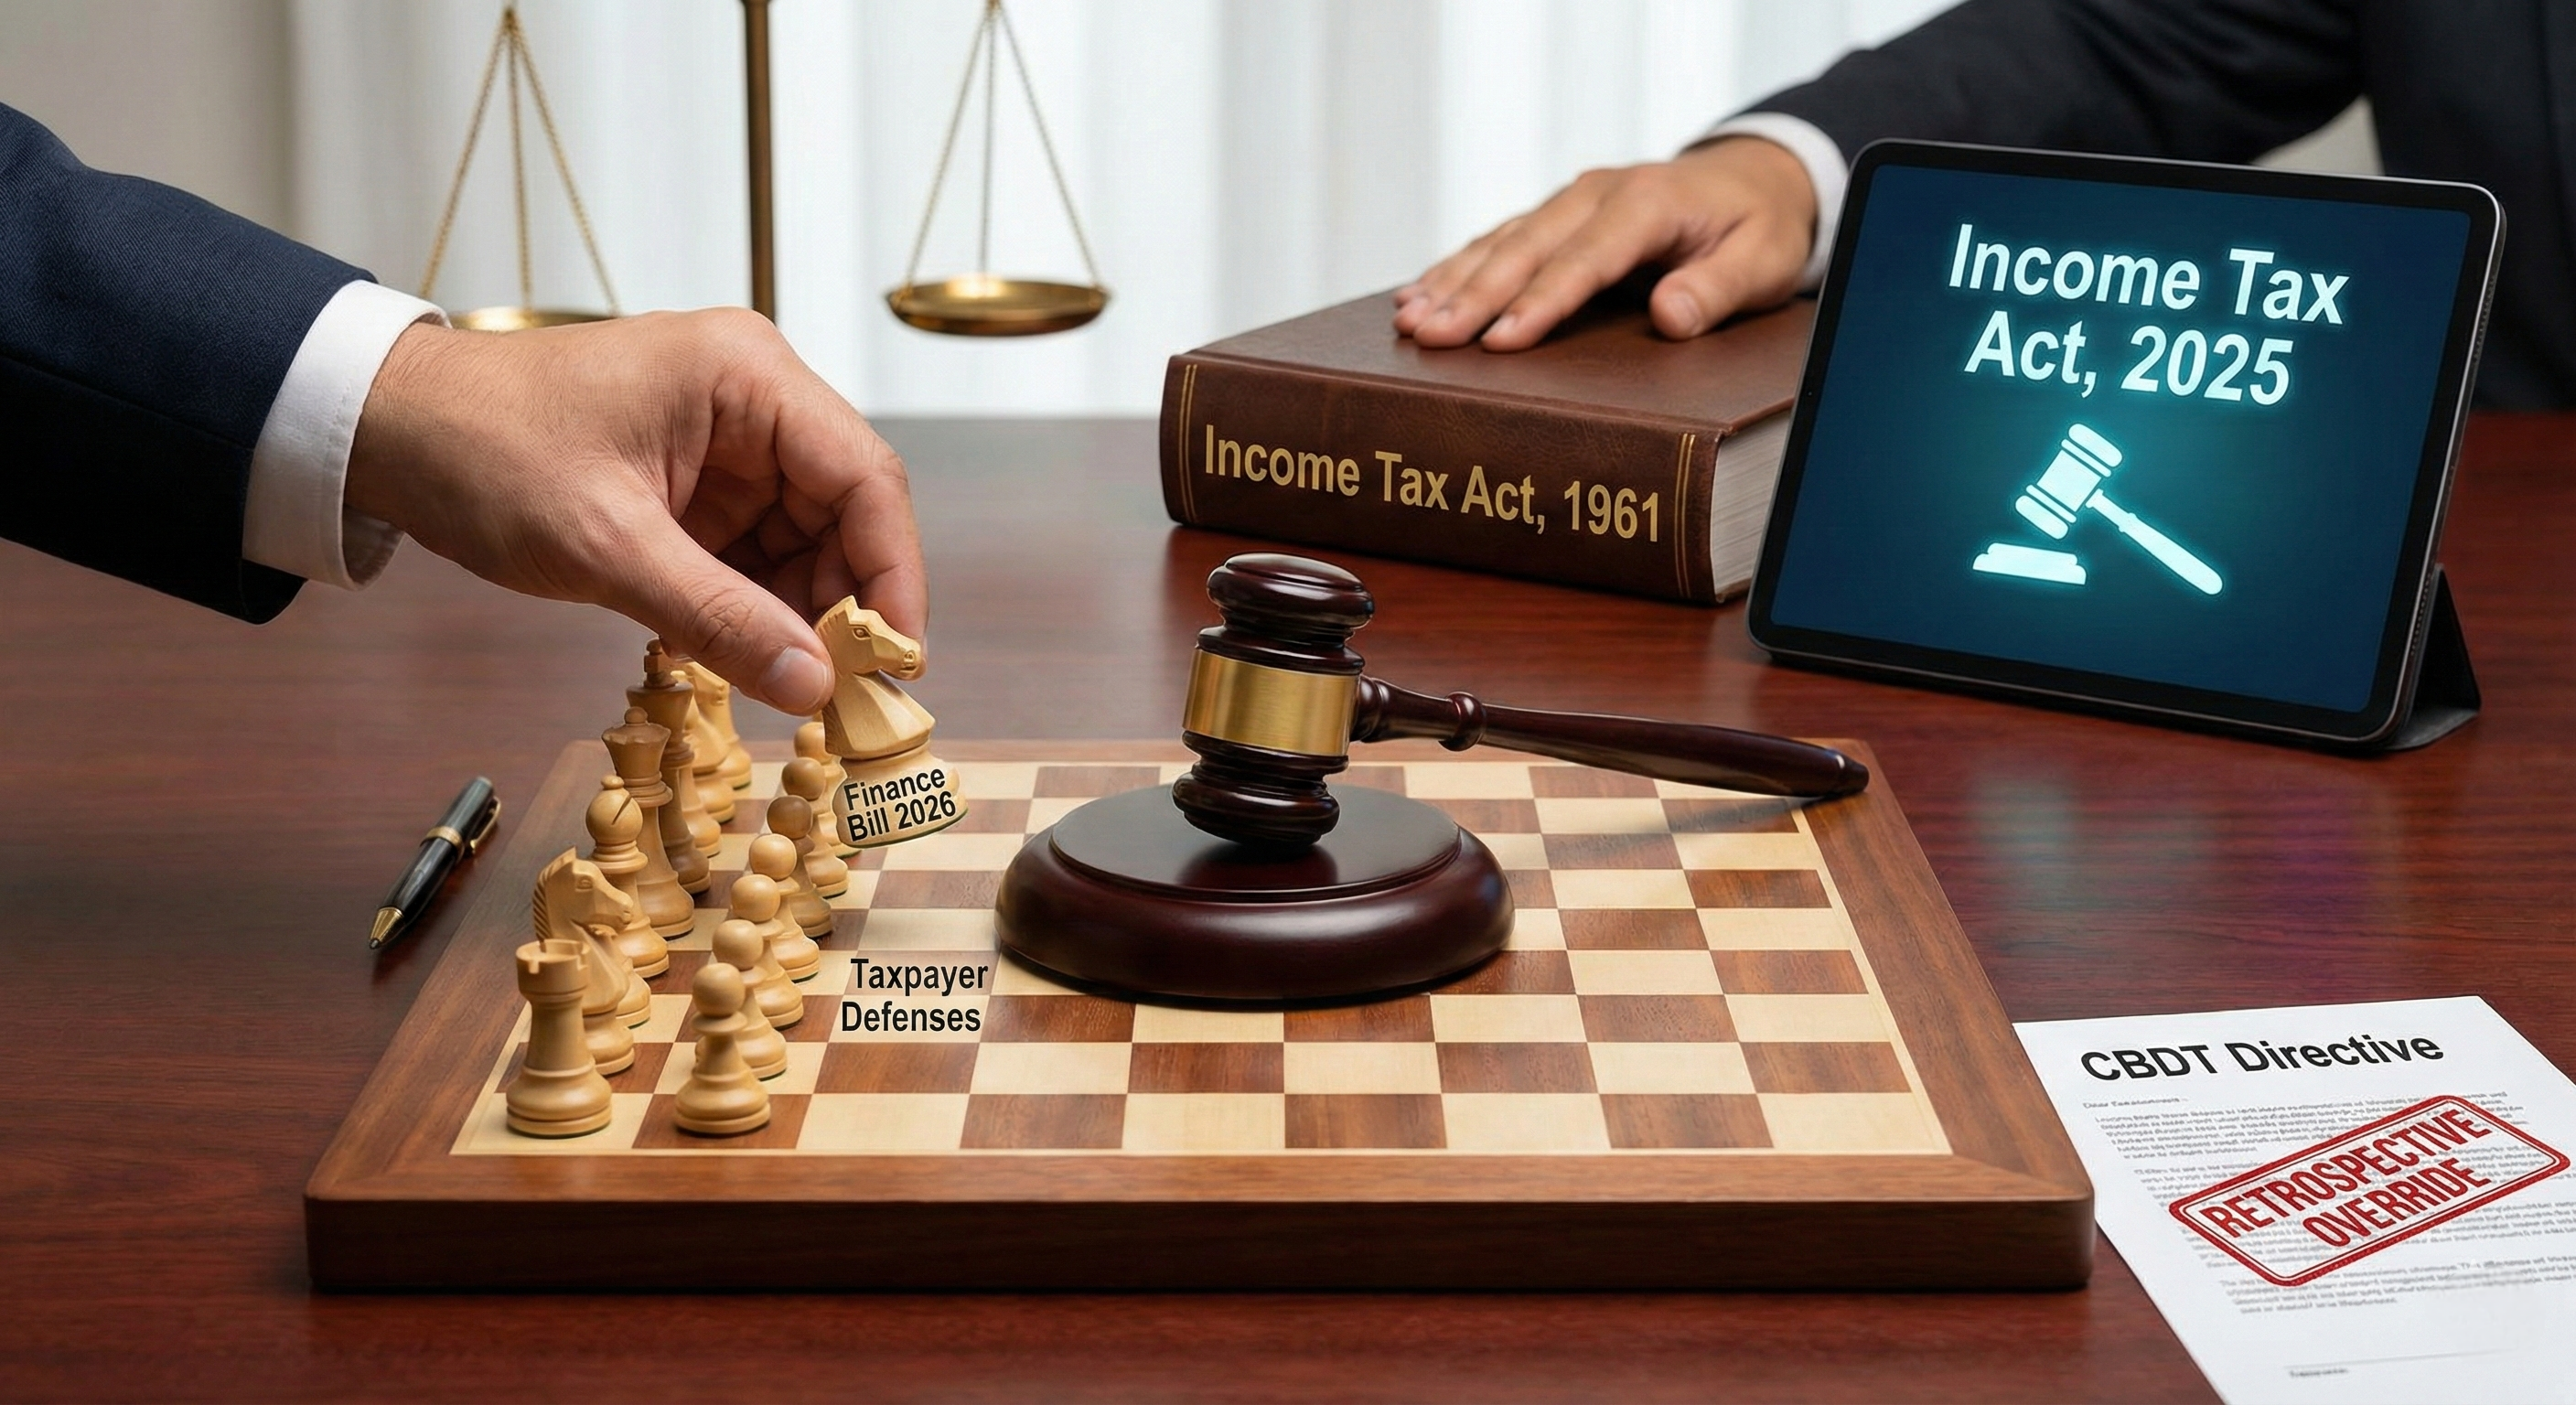
The Indian tax landscape is currently witnessing a "tectonic shift" that extends far beyond the annual budgetary ritual. With the introduction of the Finance Bill 2026 and the imminent transition to the Income Tax Act, 2025, the Central Board of Direct Taxes (CBDT) has deployed a sophisticated litigation strategy: The Legislative Override. A recent internal directive from the CBDT instructing departmental counsels to seek adjournments in matters affected by the Bill confirms that the government is moving to "statutorily cure" its losses in the High Courts and the Supreme Court.
1. The Retrospective "Cure": Turning Victories into Moot Points
The most striking feature of the Finance Bill 2026 is its aggressive use of retrospective amendments. For corporate taxpayers, this means that procedural "wins" achieved over years of litigation may be neutralized overnight.
- The End of the ‘Time-Bar’ Defense (Sections 153 & 144C): For years, the Shelf Drilling controversy provided a shield against late assessment orders. The Bill now clarifies—retrospectively from April 1, 2009—that the strict timelines in Section 153 apply only to the issuance of the Draft Assessment Order. The Final Order is now exclusively governed by Section 144C, effectively reviving billions in previously "time-barred" demands.
- Validation of Jurisdictional AO (Section 147A): The high-profile Hexaware ruling, which quashed thousands of reassessment notices issued by Jurisdictional Assessing Officers (JAOs) instead of the Faceless Centre, has been met with a legislative counter-move. New Section 147A (backdated to April 1, 2021) validates these notices, rendering jurisdictional challenges virtually redundant.
2. DIN: From Jurisdictional Mandate to Curable Defect
One of the most potent weapons in a tax lawyer’s arsenal has been the Document Identification Number (DIN). Courts have consistently held that an order without a DIN is non-est (legally non-existent).
However, Section 292BA (proposed to be retrospective from October 1, 2019) seeks to treat a missing DIN as a "curable procedural irregularity" rather than a jurisdictional fatality. This shift protects the Revenue from technical quashing and forces taxpayers to defend cases on their substantive merits.
3. The Bridge to the Income Tax Act, 2025
The Finance Bill 2026 acts as a critical bridge. While it patches the "holes" in the 1961 Act, it sets the stage for the Income Tax Act, 2025, which aims for:
- Reduced Compliance Cycles: Aligning assessment years with a more digital-first filing ecosystem.
- Litigation Settlement Windows: New provisions allow for updated returns even after a notice is issued, provided an additional 10% tax is paid a clear push toward "buying peace" over prolonged litigation.
4. Strategic Insights for TLC Clients
The CBDT's strategy of seeking adjournments is a clear signal: The Department is waiting for the Bill to become law to apply these changes to your pending cases. Our Tactical Advice:
- Audit Pending Litigations: Review all matters currently stayed or pending on grounds of limitation (Section 153) or jurisdiction (Section 148).
- Merits over Technicalities: With procedural loopholes closing, the focus must shift to a robust defense on the underlying tax merits and factual documentation.
- Constitutional Considerations: TLC is closely monitoring the potential for challenging these deep retrospective changes under the "manifest arbitrariness" doctrine of the Indian Constitution.
Conclusion
At TLC, we believe that proactive adaptation is the only defense against a retrospective regime. The transition to the 2025 Act represents a "clean slate" for the government, but for taxpayers, it requires a total re-calibration of litigation strategy.
For a confidential impact analysis of how the Finance Bill 2026 affects your pending tax disputes, reach out to our team at tlctaxlaw.com.
This article is for general information only and is not legal advice. For advice on your specific facts, please contact The Lord's Consultancy.